Many foreign exchange platforms have experienced the same problem during their roll-out:
Advertisements are posted, websites are visited and client uniforms are being followed, but clients are always reluctant to open accounts, pay money or enter into next communication.
On the surface, this is a traffic conversion problem.
But in the logic of customer decision-making in the financial sector, what really affects is whether the pages are pretty enough or not, or whether the platform presentations are written enough, but whether the customer has built a sense of trust in the first place.
For foreign exchange platforms, it is not “the platform that says how strong it is” that clients are most concerned about, but:
Is there a real subject behind the platform?
Is there a searchable regulatory information?
Is there a clear statement of compliance?
Are there basic safeguards for the client ' s financial and trading environment?
If so, does the platform have a retroactive liability structure?
If those questions were not answered clearly, the client would be hesitant.
Once clients hesitate, it becomes increasingly difficult to make a deal.
I. Clients are not interested, but unbelievably.
Many of the platforms mispercept that clients had not made a deal because of the low level of weakness, the low level of activity and the low level of incentive.
However, in financial operations such as foreign exchange, price differential contracts, digital assets, and fund investments, the true concerns of clients are usually more direct:
"Is this platform safe?"
"Is this a real company?"
“Can regulatory information be found?”
"Is there any risk when I put my money in?"
In particular, clients are now increasingly able to access information, not only through web-based publicity, but also through proactive searches for company names, regulatory numbers, licence information, platform evaluations and access money.
If the platform does not have a complete system of trust demonstration, it is likely that the client will have been lost before consulting.
II. Inadequate regulatory information that directly affects conversion rates
It is difficult for a network of financial platform officials to really address the core concerns of clients if it only displays transactional functions, intelligence systems, account opening links and revenue presentations.
When a customer enters the site, it usually quickly judges several items of information:
Do you have a license?
Which regulatory body is it?
Is regulatory information publicly accessible?
Does the subject matter of the company match the name of the platform?
Is there a risk disclosure, privacy policy, service terms and compliance statement for the network?
Can a clear scope of operations and client protection mechanisms be found?
These are not simple “decorations”, but are important factors influencing the willingness of clients to continue communicating.
For financial platforms, the clearer the regulatory information, the lower the cost of understanding by clients; the faster the cost of understanding by clients, the faster trust is built.
III. Without regulatory demonstration, the platform is vulnerable to low-cost competition
When a platform has no regulatory basis, no clear corporate information and no verifiable compliance structure, it can easily rely only on preferential activities, low-cost, high-returners and strong sales rhetoric to attract customers.
Such an approach may bring in flows in the short term, but it may put the platform into low-cost competition in the long term.
Since clients cannot distinguish between the specialization of the platform, it is only through price and activity that they judge whether it is worth trying.
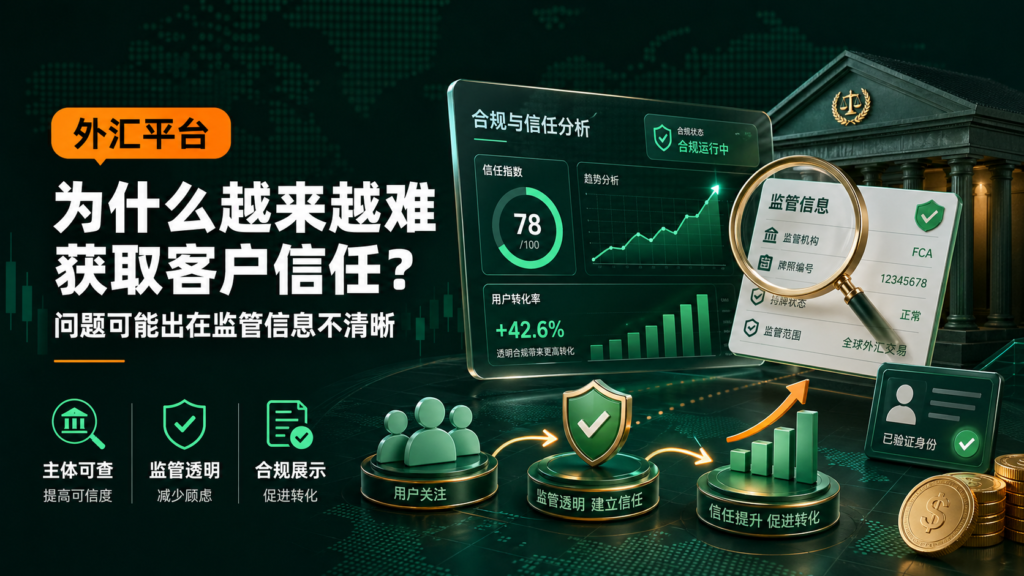
A platform with clear regulatory information can shift the focus of competition from “price” to “trust”.
Clients see the Platform ' s normative, transparent, long-term operational capacity and risk control awareness, rather than mere marketing incentives.
IV. The value of regulating licences to help the Platform complete the confidence loop
The regulation of licenses is not simply displayed on the official web.
A truly valuable approach is to turn regulatory information into part of the Platform ' s trust system.
For example:
(b) A presentation of the regulatory and compliance instructions on the front page of the official web page;
Show us on the page about our company and scope of business.
(b) Place official reference points on the regulatory information page;
Add risk disclosure and compliance tips to the customer opening page;
(b) Placement of privacy policies, service provisions, disclaimers and anti-money-laundering instructions at the foot of the page;
Use of uniform, clear and verifiable regulatory expressions in client communication.
The combination of these elements allows the client to form a complete judgement:
This is not an ad hoc platform, but a financial services platform with a subject, a rule, a compliance spirit, and a long-term business plan.
V. The platform at different stages, requiring different regulatory pathways
The demand for regulation varies at different stages of development of foreign exchange platforms.
Early platforms tend to focus more on basic corporate structures, brand credibility, payment access and network compliance demonstrations.
The growth platform will focus on regulatory directions such as MSB, FINTRAC, SEC, FCA, ASCIC, CySEC, etc., to enhance market recognition and business cooperation capabilities.
The mature platform places greater emphasis on multi-jurisdictional compliance, anti-money-laundering systems, client financial protection, institutional cooperation and long-term branding.
Thus, regulatory planning should not be based solely on “which brands are famous”, but should be designed in the context of the type of business of the platform, the customer market, the financial path, the outreach area and long-term development objectives.
The appropriate regulatory path for the platform is the regulatory path that can really improve transactional and risk reduction.
The core competition for future foreign exchange platforms is trust competition
The financial sector is entering a more transparent phase.
Clients no longer read only advertising and no longer listen only to sales presentations.
They search, compare, verify, judge.
This means that foreign exchange platforms that can develop in the long term may not necessarily be the most dynamic ones in the future, but rather better regulatory information, more transparent corporate structures, better risk statements, and more customer-trusted platforms.
For platforms that really want to operate over the long term, regulatory licences are not costs, but infrastructure.
It not only helps the Platform to reduce compliance risks, but also helps it to increase client trust, increase conversion rates, open up commercial cooperation spaces and create financial brands of more long-term value.