A Tesla CEO remuneration programme, which has lasted for many years and has been subject to litigation and shareholder disputes, has finally entered the practical phase of implementation.
According to the relevant documents submitted by Tesla to the United States Securities and Exchange Commission, Elon Mask exercised his full stock options under the 2018 CEO Performance Pay Programme on 16 June 2026, involving approximately 304 million Tesla shares.
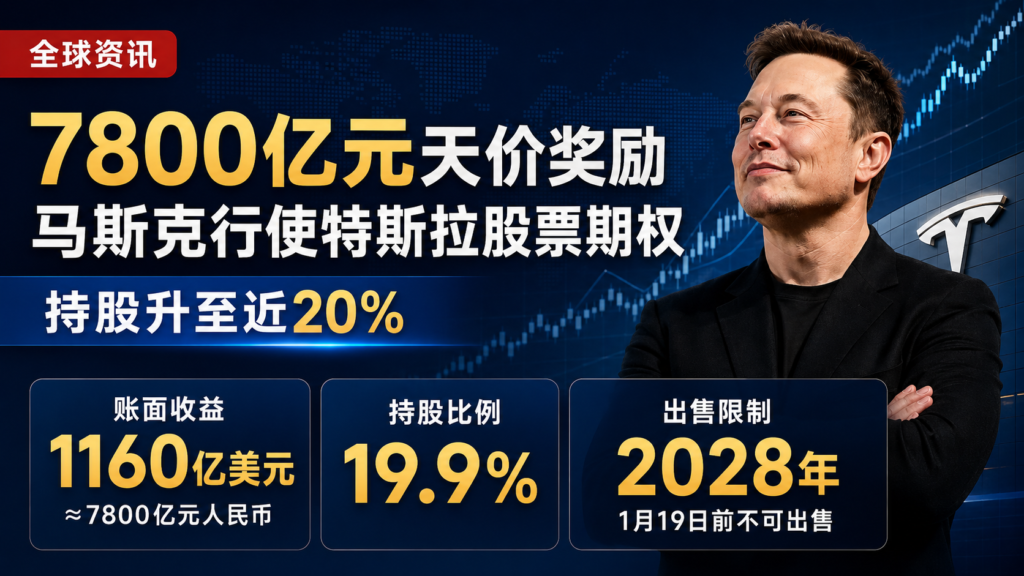
Based on the market price on the day of the right to trade, the transaction resulted in a book price difference of approximately $116 billion, or nearly $780 billion, equivalent to the RMB.
This number has rapidly attracted global attention, but it needs to be emphasized that:
The $780 billion is not the cash that Tesla paid directly to Mask, nor does it mean that Mask can now sell all shares immediately and receive the same amount.
At the heart of this incentive is the book differences between low-priced equity and current market prices, and the real value will still fluctuate as Tesla equity prices change.
I. How did Mask get about $780 billion in book revenues?
The stock options exercised by Mask were derived from the CEO performance pay scheme adopted by Tesla in 2018.
Instead of providing the traditionally fixed wage and cash bonuses to Mask, the scheme has set a number of objectives related to company performance, including:
- (a) The increase in the market value of Tesla;
- (b) Business income targets;
- (a) The adjusted profit target;
- Long-term business performance;
- Mask continues to hold corporate leadership positions.
Only when Tesla has met the corresponding performance targets could Mask buy corporate shares at a predetermined price.
The core data covered this time include:
| Item | Relevant data |
|---|---|
| Number of options exercised | About 304 million shares |
| Adjusted right-to-hand value for split shares | $23.34 per share |
| The closing price on 16 June 2026. | $404.66 per unit |
| Price difference per share | Approximately $381.32 |
| Total book value difference | Approximately $116.0 billion |
| RMB estimate | Nearly $780 billion. |
It is simply understood that Mask acquired the right to purchase Tesla shares at $23.34 per share, while the market price of the right on that day exceeded $400.
The huge gap between the two constitutes what the media call a “78 billion dollar sky price bonus”.
ii. Mask did not pay all the cash to buy shares
If approximately 304 million shares are purchased at $23.34 per share, the cost of the right to use the Mask would be approximately $7.1 billion.
The transaction was made by:
Net Share Settlement.
Under this arrangement, Mask did not come forward with approximately $7.1 billion in cash and did not sell shares on the open market to raise funds.
Tesla withheld approximately 1.75 million shares from the shares in question to offset the cost of the options, and Mask eventually acquired a net share of about 286 million shares.
This means:
- Mask exercised some 304 million shareholdings;
- Tesla withheld part of the share to offset the cost of the right to credit;
- (a) The remaining shares are to be delivered to Mask;
- The entire process did not involve the sale of Tesla shares on the open market.
Thus, the transaction was fundamentally different from “the direct payment of $780 billion in cash wages by Tesla”.
Newly acquired stocks are not expected to be sold until 2028
Although the shares in question had been converted and could bring about voting rights, Mask was not free to sell all the shares immediately.
Under the implementation arrangements, the newly acquired shares are restricted and are expected to require:
19 January 2028
The conditions for sale are met.
Before that, the reality facing Mask was that:
- (a) Holding the relevant shares;
- The right to vote may be exercised to the extent applicable;
- (a) The full stock cannot be sold off immediately;
- The final value of equities remains dependent on Tesla ' s future equity prices;
- There may also be tax and other costs involved.
If the Tesla stock price increases by 2028, the value of the related shares may increase further; if the stock price falls significantly, the current calculated book gain of $116 billion will decrease accordingly.
Thus, 78 billion yuan is only estimated on the basis of stock prices at a given date and is not a fixed final income.
IV. MAXK ' s shareholding in Tesla has risen to about 19.9%.
Following the completion of this exercise of stock options, the number of Tesla stock holdings held by Mask further increased.
Public information indicates that its Tesla shareholding ratio is close to:
19.9%。
This is not only about personal wealth, but also means that Mask's influence in Tesla shareholders' votes has further increased.
Mask had previously expressed the wish to have sufficient Tesla voting rights to maintain influence on high-risk, long-term projects such as artificial intelligence, robotics and autopilot.
With the completion of the stock conversion, his control in Tesla was further increased, but still some distance from the voting target of about 25 per cent that he had mentioned.
Why has the pay scheme been controversial for many years?
Mask ' s 2018 CEO Pay Scheme has been one of the most controversial executive incentive schemes in the area of global corporate governance since its launch.
Proponents believe that the plan has a very clear performance orientation:
- No traditional fixed wage;
- Mask will be rewarded only if Tesla reaches the difficult goal;
- (a) The binding of management interests and long-term returns to shareholders;
- The market value and size of operations in Tesla increased significantly during the plan period.
Critics, for their part:
- The incentive is too large;
- (b) The lack of sufficient independence between the Tesla Board of Directors and Mask;
- Ordinary shareholders may face dilution of shares;
- Mask allocates time between several companies;
- Large incentives may further concentrate on corporate control.
The remuneration scheme was once withdrawn by the Delaware State Court, followed by shareholder voting, legal appeals and arrangements for implementation.
The exercise meant that the pay dispute, which had lasted for many years, had entered the substantive delivery stage, but that the discussions around corporate governance, control and shareholder interests would not end.
How should “GDP of more than 140 countries” be understood?
Part of the report compares the personal wealth of Mask with the annual GDP of countries around the world and claims that it already exceeds the GDP of some 140 countries.
This comparison has a strong dissemination effect, but the two are not identical economic indicators:
- (a) The personal home is the estimated value of the asset held at a given point in time;
- GDP is the economic output generated by a country or region over a period of time;
- Mask wealth consists mainly of shares in listed and non-listed companies;
- (b) There may be significant changes in stock and corporate valuations on a daily basis;
- Personal wealth does not amount to cash that can be used immediately.
Thus, “GDP of more than 140 countries” is more suitable for a visual comparison as a wealth-scale comparison than to understand that Mask owns cash equivalent to the total assets or fiscal revenues of those countries.
What is the concept of $770 billion?
In order to give readers a more intuitive understanding of the book gain, a number of conversions were reported.
According to specific gold prices, the equivalent of approximately 9,400 tons of gold can be RM 78 billion.
If a person receives $100 million a day and goes on and on a daily basis, it will be necessary to maintain about:
7,800 days, about 21 years.
It is important to note that the phrase “one hundred million dollars a day for the lottery, which takes 246 consecutive years” appears in some short videos, which is usually calculated by the full personal wealth of Mask, rather than by a single award of about $780 billion.
In producing financial and economic content, a distinction should be made between:
- This time, the stock option book gain;
- (a) The net value of all Mask assets;
- Tesla stock value;
- SpaceX and other companies hold equity value.
Mixing of different calibres can easily lead to exaggeration or misinformation.
VIII. How will this deal affect Tesla?
1. Further increase of voting rights in Maskk
The shift of stock options to voting shares has increased Mask ' s influence in major shareholder resolutions.
2. Greater concentration of equity
The share-holding ratio is close to 20 per cent, which means that Tesla ' s reliance on personal leadership in Mask has further increased.
3. Short-term no direct open market dumping pressure
This time, net equity settlement was used, and the document showed that shares were not sold on the open market and therefore did not immediately form a multibillion dollar market offer because of the cost of the right to do business.
4. Potential future sales risks remain
After the relevant restrictions have been lifted, market sentiment and stock prices may still be affected if Mask sells shares to pay taxes, invest in other businesses or meet individual financing needs.
5. Continuing disputes over executive remuneration and corporate governance
Such large-scale equity incentives will continue to trigger discussions on the dilution of shareholders, the independence of boards and the concentration of management power.
How can the wealth of Mask grow fast?
The personal wealth of Mask is not derived primarily from wages, but from the shares of the enterprises in which it is held.
Core assets typically include:
- Tesla shares;
- SpaceX shares;
- xAI-related interests;
- Other scientific and technological enterprises and investments;
- Equity incentives that have not yet been fully realized.
This wealth structure has two distinct characteristics:
Asset value added is fast
When the corporate valuation or equity price rises under the flag, their personal wealth can increase by tens of billions of dollars in the short term.
The wealth is equally volatile.
If the valuation of Tesla or other core enterprises falls, their personal wealth may also be reduced by tens of billions of dollars in a single day.
Thus, what the media refer to as a “body” is usually a dynamic figure based on stock prices and the valuation of non-listed companies and does not amount to cash in bank accounts.
X. What is the real bet on Tesla behind the daily wager?
This incentive is not only important for the growth of personal wealth, but also reflects the deep binding of Tesla ' s future strategy on the personal leadership of Mask.
The current long-term development focus of Tesla has gradually expanded from single electric car manufacturing to:
- Artificial intelligence;
- Autopilot;
- Robotaxi unmanned taxi;
- Optimus human robot;
- Energy storage;
- Supercalculations;
- Smart manufacturing.
Proponents believe that a large stock incentive could prompt Mask to continue investing time and resources in Tesla.
But for investors, what really needs attention is not the figure of “78 billion dollars” per se, but rather:
- Is Tesla able to deliver on the promises of artificial intelligence and robotic business;
- (b) Whether the automobile business remains competitive;
- Whether Mask is able to focus on the company's business on a sustainable basis;
- Whether large equity incentives will create a comparable long-term value;
- Whether corporate governance effectively checks and balances managerial authority.
Concluding remarks
The exercise of this Tesla stock option by Mask of some 304 million shares did create an extremely rare book gain in the history of corporate executive remuneration.
The difference in book value, calculated on the basis of the daily equity value of the right, is approximately $116 billion, or the equivalent of the RMB, which is close to $780 billion.
However, an accurate understanding of the transaction requires that it be accompanied by:
- It is not a cash wage;
- The right to exercise rights would have to cover some $7.1 billion in costs;
- Tesla completes the netting by withholding part of the shares;
- New acquisitions are not expected to be sold until 2028;
- The final value will still vary with Tesla stock prices;
- The deal has also significantly increased Mask's shareholding and voting influence.
This is not only a story about personal wealth, but also a global case of business incentives, shareholder equity, corporate governance and control over science and technology companies.
Sources of information and extended reading
1. Tesla regulatory document queries
Tesla Investor Relations:SEC Filings
2. Mask options exercise and share settlement information
Sina Wei Wei Wei Wei Wei Wei Wei Wei Wei Wei Wei Wei
3. $780 billion in book proceeds and 2028 sales restrictions
Daily economic news: Mask's got a price bonus.
4. Tesla 2018 CEO performance award context
United States Securities and Exchange Commission: Tesla Shareholder Paper
Disclaimer
This paper is organized on the basis of public regulatory documents and media coverage and is used only for global financial information and corporate governance case analysis and does not constitute portfolio investment advice.
Stock prices, corporate valuations, and personal wealth change with the market.